


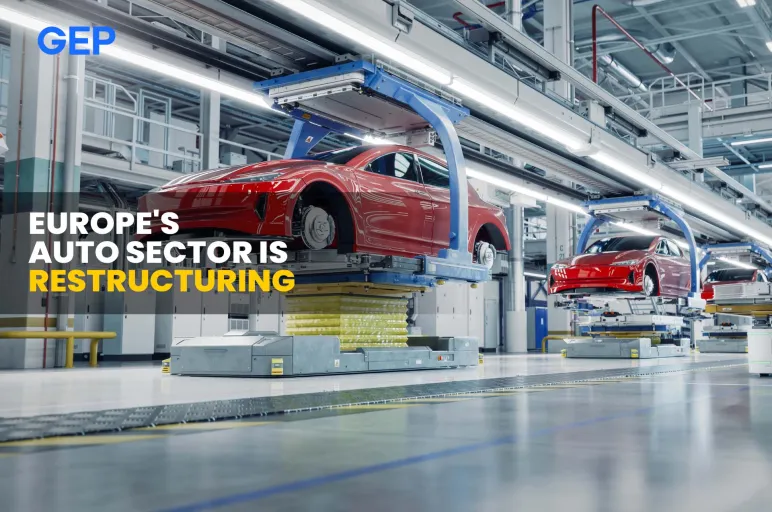
Europe's Automakers Are Cutting Deep. Here's What It Means for Procurement
- Jaguar Land Rover, Volkswagen, Aston Martin and Bentley have all announced major layoffs or cost programs in 2026, and Germany's factory data shows the strain is already visible in output.
- The pressure is moving down the supply chain, from OEM overhead budgets into Tier 1 and Tier 2 suppliers who built their own forecasts around steady automaker demand.
- Procurement teams tied to the automotive sector should get ahead of it: stress-test supplier finances, model cost reductions before they're mandated, and revisit sourcing footprints built for a different demand picture.
October 21, 2026 | Automotives 5 minutes read
Jaguar Land Rover opened a voluntary redundancy program this month, targeting roughly 4,000 job cuts among salaried and management staff over the next two years to save about £1.7 billion, or $2.3 billion, according to CNBC and Fox Business. Hourly assembly-line staff are excluded. The Tata Motors-owned automaker wants to lower its global break-even point to 300,000 vehicles a year, a target set against a backdrop of a cyberattack last year that halted production for weeks, U.S. tariffs, and share losses to Chinese rivals. JLR's fiscal first-quarter profit fell 66% to £66 million as revenue dropped 9.6% to £6 billion.
The move isn't an outlier. Four days earlier, Volkswagen's supervisory board unanimously approved “Future Plan 2030,” a restructuring that adds 50,000 job cuts to the 50,000 already agreed, bringing the group's total to roughly 100,000 positions by decade's end, Bloomberg reported. Europe's largest automaker says its German plants are running about 500,000 vehicles a year above what demand requires.
Earlier this year, Aston Martin cut up to 20% of its workforce for roughly £40 million in annual savings, and trimmed its five-year capex plan by £300 million, while Bentley eliminated about 275 roles (6% of its workforce) as it scaled back its own EV timeline.
Germany's Federal Statistical Office reported industrial production fell 1.1% in July (the steepest drop since August 2025), with a 9.2% decline in automotive output driving most of the fall, tied to a multi-week production shutdown. Automotive new orders fell 12.5% for the month.
Strengthen Your Automotive Supply Chain Against Disruption
Learn how procurement teams in the automotive sector can reduce supply risk and stay ahead of volatility
Three Forces, One Squeeze
What's striking about this run of announcements isn't any single company's numbers. It's how similar the explanations are, with every automaker pointing to the same three pressures in different proportions.
The first is trade policy. JLR, Aston Martin and Volkswagen all cite U.S. tariffs as a direct hit to margins on vehicles built in the UK and Germany for American buyers. The second is China. ACEA data cited by FXCM shows EU vehicle imports from China rose 30.7% year-over-year in 2025, topping one million units, and Chinese brands' share of Western Europe's battery-EV market climbed from 9.4% to 14.2% in a single year, according to Forbes reporting on Schmidt Automotive Research data — even after EU tariffs of up to 35.3% on Chinese-built EVs. The third is simply overcapacity: European plants built for a bigger, faster-growing market than the one that materialized.
Not everyone reads the moment the same way. Investors, for one, seem relieved rather than alarmed. Volkswagen's shares jumped on the news, with Deutsche Bank analysts calling the plan a “fundamental breakthrough” that could create a “halo effect” across the German auto sector, per CNBC. Unions, unsurprisingly, see it differently, and are pushing for guarantees on the roughly 30,000-strong hourly workforce that remains outside these programs for now.
For procurement and supply chain leaders, the read-through matters more than the politics. Overhead cuts at the OEM level rarely stay contained to head office. Indirect spend — professional services, contracted labor, discretionary capex — is typically the first place a CPO is asked to find savings when a parent company sets an aggressive target.
And because JLR, VW, Aston Martin and Bentley all supply from overlapping pools of Tier 1 and Tier 2 vendors, a slowdown at one accelerates the exposure at the others. Smaller suppliers with concentrated automotive customer bases (machine tooling, specialty metals, interior components) carry more risk than their order books currently show, particularly if a plant slowdown or shift change hits with little warning, as it did with JLR's cyberattack last year and Germany's July production halt.
Plan Your Supplier Strategy Before the Next Round of Cuts
Talk to GEP's supply chain experts about supplier risk monitoring, footprint reassessment and network optimization
How Procurement Can Get Ahead of the Next Round of Cuts
A few moves can help procurement teams get ahead of this cycle instead of reacting once cuts land on their desk:
- Reassess supplier financial health now, particularly among Tier 2 and Tier 3 vendors whose revenue concentrates in one or two OEM accounts that are currently cutting output or headcount.
- Build your own indirect-spend case before it's handed to you. A zero-based budgeting exercise run proactively puts procurement in the room shaping the target, rather than absorbing one set from above.
- Revisit network and footprint assumptions. Plant slowdowns, shift changes and volume shifts across multiple automakers can move the optimal sourcing locations and freight lanes procurement planned around a year ago.
- Add flexibility to new supplier agreements, such as shorter terms and volume-flex clauses, given how quickly production plans are moving across the sector right now.
- Formalize supplier risk monitoring rather than relying on quarterly check-ins. Supply chain risk and resilience services aggregate risk signals across a supplier base so disruptions surface before they hit a purchase order.
- Ground network decisions in scenario modeling, not ad hoc cuts. GEP's network strategy and optimization work combines digital footprint analysis with cost-to-serve modeling, an approach that has more than doubled the impact of a standalone cost review for some manufacturing clients.
The automakers making headlines are betting that leaner, more disciplined organizations will outlast this cycle. Procurement teams in their supply base face the same choice. The ones that plan the restructuring on their own terms, rather than someone else's timeline, will come out of it in better shape.
Unlock GEP’s - AI-Native Procurement Software
BLOG CATEGORIES
FAQ’s
Overhead cuts at the OEM level rarely stay contained to head office. The pressure moves down the supply chain to Tier 1 and Tier 2 suppliers, many of whom built their forecasts around steady automaker demand. Suppliers with concentrated automotive customer bases, such as machine tooling, specialty metals and interior components, often carry more risk than their order books show. Because several automakers draw on overlapping supplier pools, a slowdown at one OEM can increase exposure at the others.
Procurement teams should act before the impact reaches their desk. Start by reassessing supplier financial health, especially among Tier 2 and Tier 3 vendors that depend on one or two OEM accounts. Build your own indirect-spend case, such as a proactive zero-based budgeting exercise, so procurement helps shape savings targets rather than absorbing them. Review sourcing locations and freight lanes against the new demand picture, and add flexibility to new supplier agreements through shorter terms and volume-flex clauses.
Move from quarterly check-ins to formal, continuous supplier risk monitoring, so disruptions surface before they hit a purchase order. Pair this with scenario modeling for network and footprint decisions, instead of relying on ad hoc cuts. Combining digital footprint analysis with cost-to-serve modeling helps teams make sourcing decisions that hold up as production plans shift across the sector.